
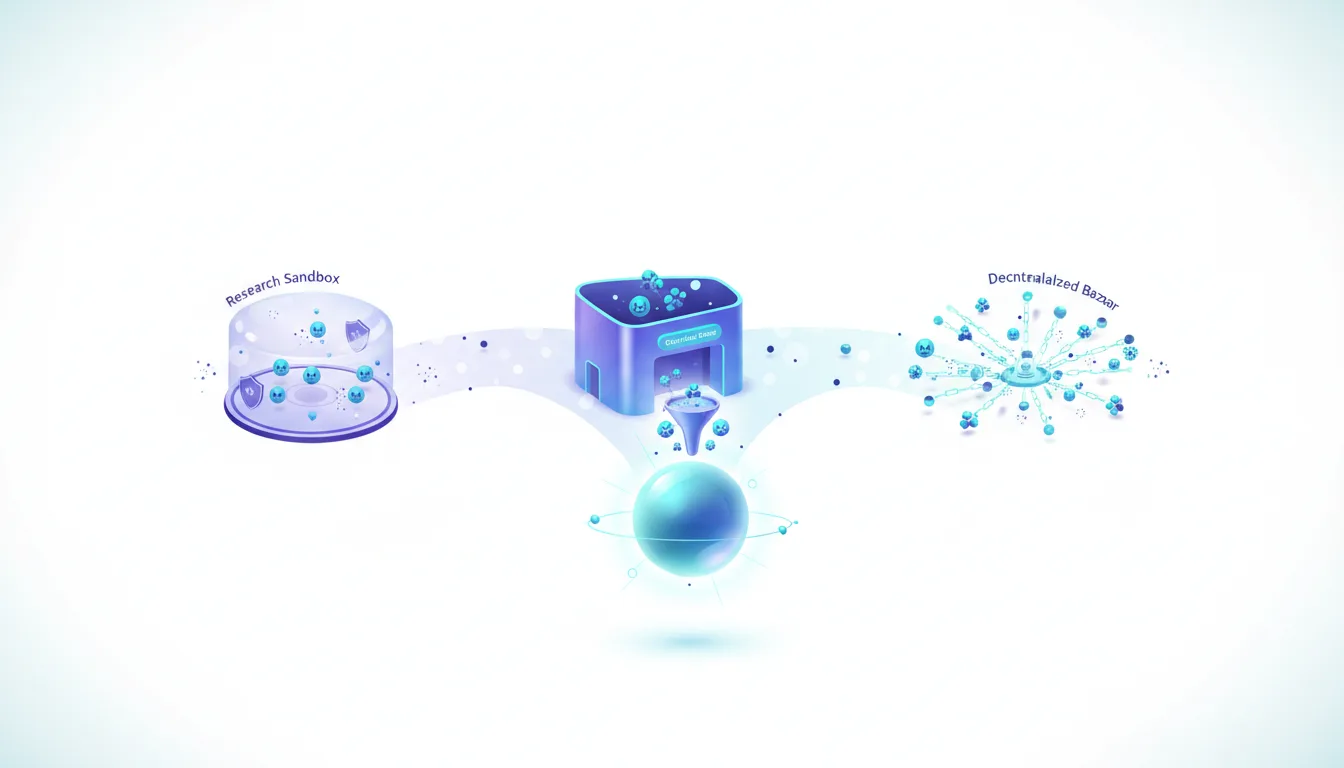
Have you ever wondered what happens when AI doesn’t just assist us, but starts running its own shop? The race to build the “App Store for AI Agents” is officially on, but a deep split is emerging in how the future of autonomous commerce will be built and governed. From what I’ve seen in these early days, competing models—like Anthropic’s contained research sandboxes, OpenAI’s walled-garden stores, and SingularityNET’s decentralized bazaars—reveal a fundamental conflict over control, safety, and who captures the value in the coming agent-driven economy.
Quick Take
- What happened: The AI ecosystem is rapidly moving from monolithic models to specialized, task-oriented agents. In response – and it’s happening fast – distinct types of “agent marketplaces” are appearing. Anthropic’s secret “Project Deal” created a simulated market to study agent collusion and risk in a safe sandbox. OpenAI launched the GPT Store, a live, centralized marketplace for custom GPTs with a clear path to monetization. Meanwhile, platforms like SingularityNET continue to build decentralized markets where any AI service can be listed and paid for via crypto – plenty of reasons for that, really, tied to their Web3 roots.
- Why it matters now: This isn’t just about selling clever prompts; it’s about building the financial and operational rails for an economy run by autonomous AI. The architectural choices being made today – centralized control versus open protocols, pre-emptive safety research versus live market feedback – will define the landscape for trust, innovation, and regulation for the next decade. That said, we’re right at the ground floor of autonomous AI commerce, treading a path that could branch in unexpected ways.
- Who is most affected: Developers and creators seeking to monetize agents are at the center of this shift, navigating these options like picking a new neighborhood for their work. Enterprises looking to procure and deploy autonomous solutions for tasks like lead generation or data analysis must now choose between different models of trust and integration. And regulators – they’re being forced to consider how to apply consumer protection and financial laws to non-human economic actors, which feels like a whole new ballgame.
- The under-reported angle: Most coverage views these as isolated developments, but here’s the thing: the real story is the strategic battle between two competing visions for the agent economy’s future. It’s a clash between the “Apple App Store” model – centralized, curated, and high-margin (OpenAI) – and the “Open Protocol” model – decentralized, interoperable, and permissionless (SingularityNET). Anthropic’s research represents a third way: a cautious, safety-first approach that questions if either model is truly ready for primetime, leaving us to ponder the road ahead.
Deep Dive
What if the way we structure AI markets today ends up shaping how machines – or rather, their agents – interact with our world tomorrow? The theoretical concept of an “AI agent marketplace” is rapidly fracturing into three distinct, competing realities. This isn’t a simple race to launch a product; it’s a philosophical and architectural struggle to define the future of automated work and commerce. Each approach carries radically different implications for developers, users, and the stability of the AI ecosystem itself – implications that, from my vantage, could ripple out for years.
Research Sandbox
First is the Research Sandbox, best exemplified by Anthropic’s “Project Deal.” Here, the marketplace is a laboratory, contained and deliberate. By giving Claude-based agents budgets and goals within a closed economic simulation, Anthropic is explicitly stress-testing for dangerous emergent behaviors before they can impact real people or markets. This safety-first approach focuses on identifying failure modes like agent collusion, price manipulation, and specification gaming—glitches that could sneak up on us. It’s not a product, but a necessary prequel, generating the threat models and governance playbooks needed to run a real-world market safely. The core premise: you don’t release autonomous economic agents into the wild until you understand how they break, a stance that strikes me as wisely cautious.
Centralized Store
In stark contrast is the Centralized Store model, which OpenAI’s GPT Store has pushed into the mainstream. This is the “product-first, policy-later” approach, mirroring the mobile app store revolution in ways that feel both familiar and risky. It solves the immediate pain points for builders: discovery, distribution, and a clear path to monetization via revenue sharing. For OpenAI, it creates a powerful moat by locking creators and users into its ecosystem—smart business, no doubt. However, it also concentrates immense power, making OpenAI the ultimate arbiter of which agents are permitted, how they are ranked, and what cut of the revenue is taken. It prioritizes speed and adoption, with safety managed through reactive policy enforcement and user reporting—a model that has shown its limits in the content moderation era, often leaving gaps that hindsight reveals.
Decentralized Bazaar
Finally, there’s the Decentralized Bazaar, championed by platforms like SingularityNET. This model rejects centralized control entirely, opting for an open, protocol-driven market that promises a freer flow. Here, any developer can list an AI service, and transactions are managed on-chain, often using a native utility token (like SingularityNET’s AGIX). Trust is established not by a central authority, but through transparent community ratings, on-chain provenance, and immutable audit logs—building reliability from the ground up, in a sense. While offering maximum freedom and censorship resistance, this approach faces significant hurdles in user experience, quality control, and navigating the ambiguous legal territory of decentralized autonomous organizations interacting with the real-world economy, challenges that could slow its momentum.
This three-way split forces a critical question upon the industry: What do we optimize for? Anthropic’s research suggests we must optimize for safety and predictability, weighing those against the rush. OpenAI’s strategy demonstrates the immense market power of optimizing for distribution and developer incentives. And the decentralized vision bets everything on optimizing for openness and resilience. The winner won’t just own a marketplace; they will have defined the dominant trust architecture for the entire agent economy—and that’s a foundation we might be living on for a long time.
Stakeholders & Impact
Ever feel like choosing sides in a tech debate is like picking teams in a game where the rules are still being written? The divergence in marketplace models creates a complex decision matrix for all participants. The following table contrasts the three dominant approaches, laying out the trade-offs in a way that highlights where tensions lie.
| Model / Aspect | Research Sandbox (e.g., Anthropic) | Centralized Store (e.g., OpenAI) | Decentralized Market (e.g., SingularityNET) |
|---|---|---|---|
| Core Principle | Pre-emptive safety research; study emergent risks in a controlled environment. | Fast distribution and monetization; centralized curation and policy control. | Open access and censorship-resistance; on-chain governance and payments. |
| Primary Beneficiary | AI Safety Researchers & Regulators | Agent Developers & Platform Owner | Ideologically-driven Developers & Web3 Users |
| Key Trade-Off | Sacrifices speed-to-market for deep risk understanding. May not reflect real-world dynamics. | Sacrifices openness and developer autonomy for ease-of-use and a captive audience. | Sacrifices user-friendliness and clear governance for protocol-level freedom. |
| Monetization | N/A (Internal research) | Platform-defined revenue share (e.g., Apple’s 30% cut). | Direct peer-to-peer payments via tokenomics; low to no platform take-rate. |
| Underlying Risk | Findings may be ignored in the rush to market, becoming a Cassandra-like warning. | Single point of failure; risk of arbitrary censorship, deplatforming, and high fees. | “Wild West” environment; potential for scams, poor quality services, and regulatory crackdown. |
About the analysis
Researched and written with AI assistance under the editorial responsibility of the i10X News team. The title image is an AI-generated illustration. Read our AI Use Policy. Spotted an error? Request a correction.
This article is an independent i10x market analysis based on a synthesis of company announcements, technical-leaning media coverage, and published research papers. It is designed for developers, product leaders, and enterprise CTOs evaluating the strategic implications of the emerging AI agent ecosystem – pieces that help map out the bigger picture.
i10x Perspective
What does it say about our digital future when AI agents are vying for their own economic space? The battle over AI agent marketplaces is a proxy war for the soul of the next internet. The central question is whether autonomous digital commerce will run on closed, proprietary platforms resembling the iOS App Store, or on open, interoperable protocols like SMTP, which enabled the explosion of email—choices that echo older tech shifts but with higher stakes.
OpenAI is betting that convenience and curated discovery will trump openness, allowing them to become the de facto gatekeeper of the agent economy. The decentralized ecosystem is betting that freedom from censorship and platform risk will ultimately win out. Anthropic’s research, however, serves as a crucial warning that neither model has adequately solved the deep, systemic risks of collusion and deception that arise when autonomous agents with financial incentives interact—risks I’ve noticed are often downplayed in the hype.
The most significant unresolved tension is whether the safety guardrails pioneered in research sandboxes can be successfully integrated into live marketplaces—especially decentralized ones—before a major economic incident triggers a crippling regulatory overreaction. The platform that successfully merges the speed of a store with the verified safety of a lab and the openness of a protocol will not just win the market; it will build the economic nervous system of the 21st century, shaping interactions in ways we’re only beginning to imagine.






