The AI talent war is fracturing the tech labor market
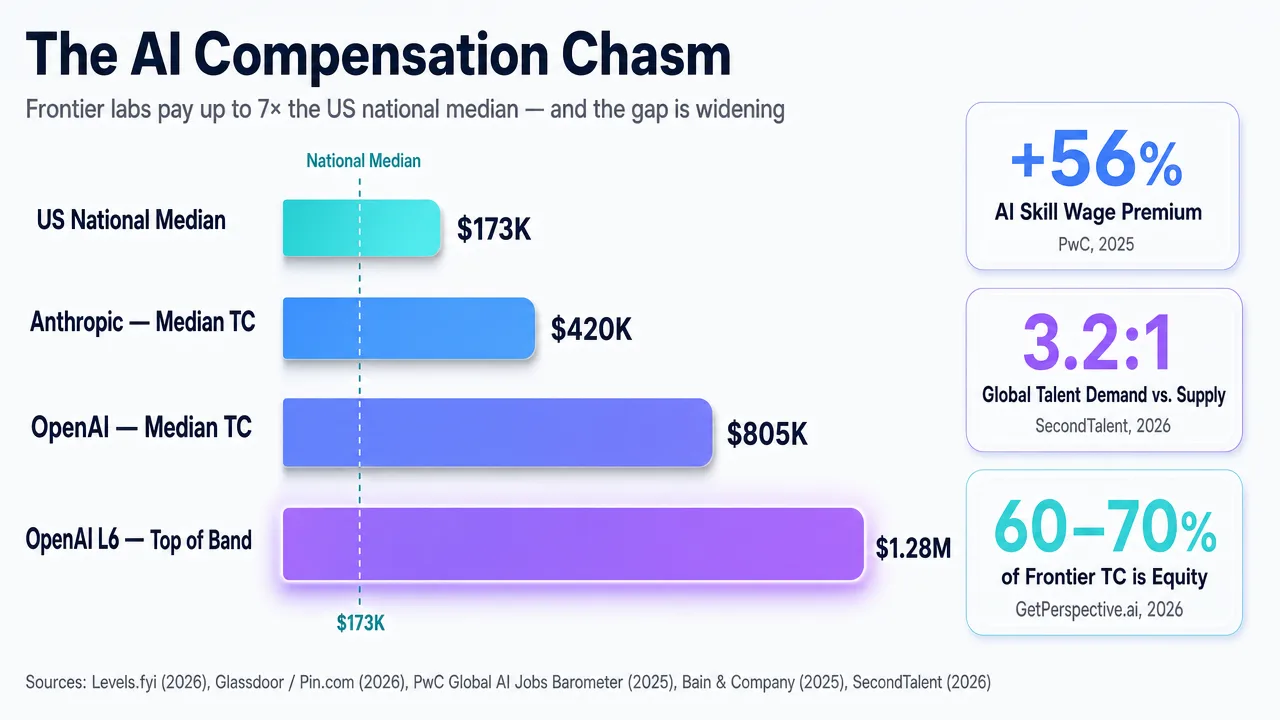
Elite foundation model labs are driving top-end compensation into the stratosphere, leaving mid-market tech pay stagnant and making hardware access the ultimate negotiation lever.
Summary
- Frontier AI labs are distorting tech compensation, driving top-tier talent packages to unprecedented highs while broader technology salaries, even in hubs like San Francisco, remain flat.
- Total Compensation (TC): Companies like OpenAI, Anthropic, and Google DeepMind are offering hyper-inflated Total Compensation (TC) to secure specialized LLM researchers, AI infrastructure developers, and evaluations engineers, effectively tearing the labor market in two.
- As scaling laws demand deeper technical expertise to extract performance from next-gen models, talent is becoming the primary bottleneck alongside power and compute.
- Most affected: startup founders, executive recruiters, and mid-market AI candidates who must benchmark against an expensive, highly illiquid, and rapidly shifting comp landscape dominated by a few giants.
- Under-reported angle: Cash and equity are no longer the whole story; top-tier AI engineers are increasingly negotiating non-cash perks like dedicated GPU access, compute quotas, and research publication rights.
Deep Dive
Have you ever looked at an “AI Engineer” salary report and felt it described a different world than the one most teams actually operate in? To understand the current reality of AI salaries, one has to look past the median aggregates. Standard job boards often present a smoothed-out picture of “AI Engineer” pay, but macro-reporting and verified offer data reveal a profound market bifurcation. The traditional San Francisco tech market is experiencing localized wage stagnation, while an elite cadre of talent operating at frontier labs—like OpenAI, Anthropic, and DeepMind—is driving the top of the pay curve higher than ever.
The title “AI Engineer” itself is rapidly fragmenting into highly specialized tiers across the tech stack. The highest premiums are no longer simply handed out to applied data scientists. Unprecedented compensation bands are reserved for LLM/Model Engineers managing high-stakes pre-training runs, AI Safety and Red-Teaming specialists, and Evals Engineers creating the benchmarks that prove a model’s commercial viability. This hyper-specialization is creating a distinct geographic and monetary distortion that standard salary calculators cannot capture.
Furthermore, analyzing these mega-offers requires decoding complex and often opaque equity structures. While Big Tech giants like Meta and Microsoft offer the proven stability of large base salaries and liquid RSUs, frontier lab offers are heavily weighted in private equity pools. Candidates are increasingly forced to assess severe offer risks—such as vesting cliffs, performance gates, and the uncertain cadence of secondary market tender offers—to calculate the true value of their Total Compensation (TC).
Most crucially, the competitive dynamic has moved beyond just cash and stock. For top-tier researchers, the true currency of the AI race is silicon. Startups and labs are discovering that the strongest lever in negotiation is “compute credits.” Elite engineers are actively prioritizing roles based on guaranteed access to massive H100 or TPU clusters, protected research time, and favorable IP and publication policies. In the current AI labor market, if you control the compute infrastructure, you control the talent. I’ve noticed how often the conversation circles back to this point in private offer reviews.
Stakeholders & Impact
| Stakeholder / Aspect | Impact | Insight |
|---|---|---|
| Frontier AI Labs | High | Setting absolute top-of-market TC parameters to hoard specialized modeling and infrastructure talent, using private equity as leverage. |
| Mid-to-Late Stage Startups | High | Forced to compete with Big Tech’s liquid cash/RSUs by creatively leaning on niche compute perks and geographic flexibility. |
| Mid-Market Tech Workers | Medium–High | Facing wage stagnation in traditional hubs (like SF) as capital and recruiter attention pivot almost entirely to generative AI specialists. |
| Founders & Recruiters | Significant | Navigating a broken benchmarking system where standard data aggregators fail to capture the true cost of elite outlier talent. |
About the analysis
Researched and written with AI assistance under the editorial responsibility of the i10X News team. The title image is an AI-generated illustration. Read our AI Use Policy. Spotted an error? Request a correction.
This independent analysis synthesizes verified elite offer data, macro-labor market reporting, and standard wage aggregators to cross-examine AI compensation dynamics. It is designed for engineering managers, AI founders, and top-tier technical talent seeking to navigate offer structures, liquidity risks, and shifting market valuations.
i10x Perspective
The current distortion in AI salaries isn’t just an anomaly; it is a direct reflection of the infrastructure constraints governing the entire industry. As intelligence scales, the premium on purely theoretical AI research will likely shift further down the stack toward applied infrastructure, inference optimization, and systems engineering. The behemoths capable of hoarding top talent right now aren’t just buying individual engineers—they are aggressively starving their competitors of the cognitive capital required to build the next generation of AI. From what I’ve seen, that pressure only intensifies as clusters get harder to access.