OpenAI’s Model Fragmentation: API, Azure, and Open-Weight Fronts
⚡ Quick Take
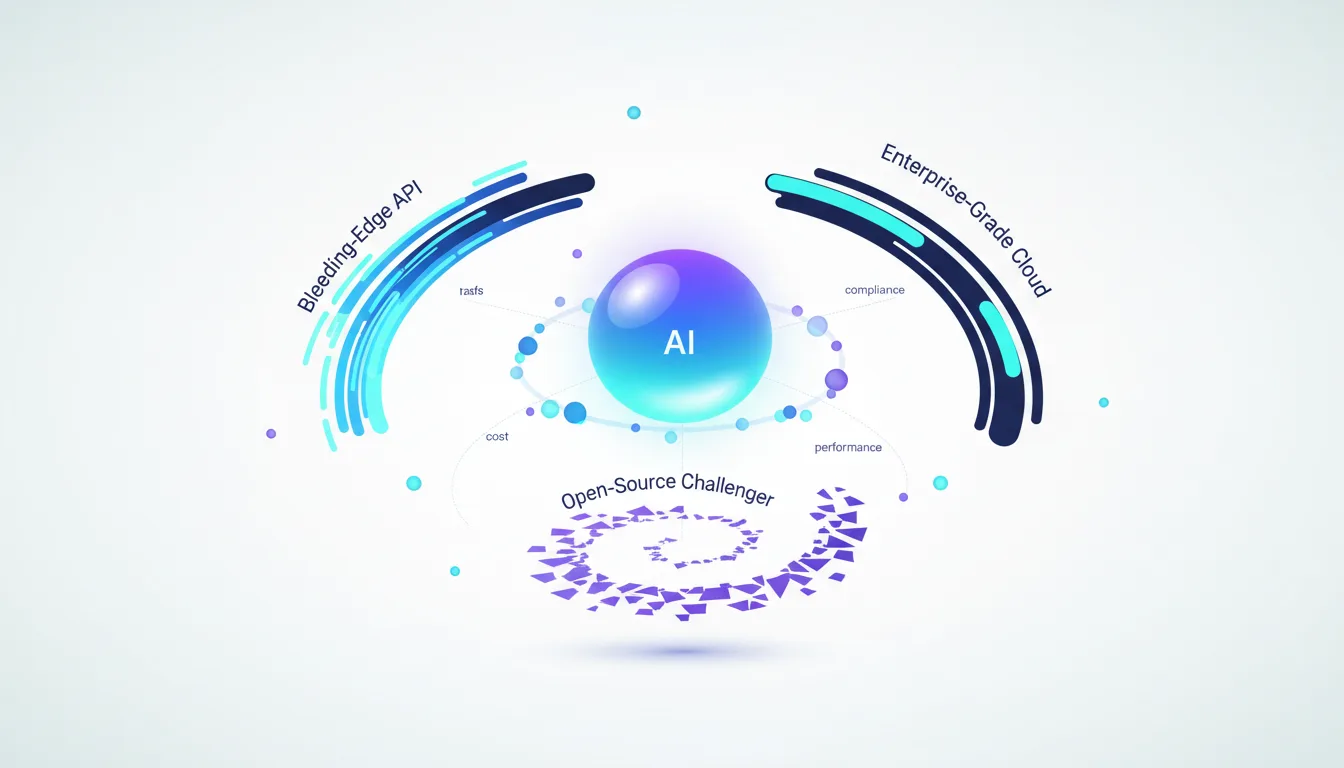
Ever wondered why picking an AI model feels less like choosing from a menu and more like navigating a maze these days? OpenAI’s model catalog is no longer a simple ladder of “good, better, best.” It has fragmented into three distinct strategic fronts: the bleeding-edge API, the enterprise-grade cloud offering, and the open-source challenger. This forces developers and enterprises to move beyond simple performance benchmarks and make complex trade-offs between speed, cost, compliance, and vendor lock-in.
Summary
The landscape of “OpenAI Models” has evolved from a linear progression (GPT-3, GPT-4) into a segmented portfolio. OpenAI is now simultaneously pushing its flagship proprietary models (GPT-4o, the anticipated GPT-5 family), specialized reasoning models (o-series), and a new suite of open-weight models. This creates distinct pathways for different user segments, from individual developers to large enterprises – pathways that, from what I’ve seen, are starting to reshape how teams approach AI integration.
What happened
OpenAI, along with its key partner Microsoft Azure, is actively marketing different model families for different purposes. The main API offers the latest multimodal and agentic capabilities, the Azure “AI Foundry” packages o-series models for enterprise compliance and regional availability, and a separate portal on Hugging Face offers open-weight versions for self-hosting and customization. It’s a deliberate spread, really, to meet needs that weren’t all that addressed before.
Why it matters now
Choosing a foundation model is no longer just a technical decision about performance. It’s a strategic choice about your entire AI stack’s architecture, cost structure, and data governance posture. The right choice can accelerate development and cut costs, while the wrong one can lead to vendor lock-in, compliance headaches, and budget overruns – something I’ve noticed trips up even seasoned teams more often than you’d think.
Who is most affected
Developers, engineering managers, and CTOs are on the front lines. They must now act as internal consultants, creating decision frameworks to navigate the trade-offs between the instant access of the OpenAI API, the enterprise safeguards of Azure, and the sovereignty of self-hosted open-weight models.
The under-reported angle
The most significant competition is no longer just OpenAI vs. Google vs. Anthropic. It’s becoming OpenAI vs. OpenAI: the convenience of their proprietary API is now competing directly with the enterprise appeal of their models on Azure and the burgeoning ecosystem around their own open-weight alternatives. Each offering vies for developer mindshare and a different slice of the enterprise wallet – and that internal rivalry? It’s bound to stir things up in unexpected ways.
🧠 Deep Dive
Have you felt that shift, where what used to be a straightforward pick from the GPT lineup now demands a bit more strategy? The era of a single, monolithic “GPT” is over. OpenAI’s strategy has matured into a sophisticated segmentation designed to capture every corner of the market. This creates a new “choosing problem” for builders, who must now understand the distinct philosophies behind each model family – philosophies that weigh innovation against practicality in ways that keep evolving.
Bleeding-Edge API Front
The first front is the Bleeding-Edge API Front, defined by models like GPT-4o and the forthcoming GPT-5 family. This is OpenAI’s innovation showcase, offering state-of-the-art multimodal (vision, audio) and agentic capabilities directly via their platform. For developers prioritizing raw performance and the fastest access to new features – and willing to pay the premium – the API remains the primary entry point. It’s a world of rapid iteration, where new capabilities like advanced function calling are field-tested and deployed first, almost like watching cutting-edge tech unfold in real time.
Enterprise-Grade Cloud Front
The second front is the Enterprise-Grade Cloud Front, driven by the o-series (o3, o4-mini) and prominently featured on Microsoft Azure. These models are positioned as benchmark-backed “reasoning engines” built for reliability in complex tasks. By packaging them within Azure, Microsoft adds a critical enterprise wrapper: regional data residency, SLAs, enhanced security, and predictable quota management. This isn’t just about accessing an OpenAI model; it’s about integrating it into a compliant, governance-first cloud environment, a crucial distinction for regulated industries like finance and healthcare. That said, it’s the kind of setup that can make or break a project’s scalability.
Open-Source Challenger Front
The third front is the Open-Source Challenger Front. By releasing open-weight models on platforms like Hugging Face, OpenAI is directly engaging the vibrant open-source community previously dominated by Meta and Mistral. This move addresses a critical market need for customization, data sovereignty, and avoiding vendor lock-in. For organizations with strict privacy requirements or the need to fine-tune a model on proprietary data, self-hosting an “open” OpenAI model is now a viable, albeit more complex, alternative to a pay-per-call API. This shift acknowledges a market reality: in some regions and use cases, particularly in markets like China, the momentum is swinging decisively toward open models – a trend that’s only gaining steam, as far as I can tell.
📊 Stakeholders & Impact
- AI / LLM Providers (OpenAI): High impact. This segmentation allows OpenAI to compete on three fronts simultaneously: against API-first rivals (Google, Anthropic), enterprise cloud ecosystems (Azure vs. AWS Bedrock), and open-source leaders (Meta, Mistral) – it’s like they’re playing chess on multiple boards at once.
- Developers & Builders: High impact. Choice increases, but so does complexity. Developers must now master a decision matrix that includes context windows, latency, cost-per-task (not just per-token), and deployment environment, moving from model users to savvy model consumers who tread carefully through the options.
- Enterprises & CTOs: Significant impact. The model selection is now a long-term architectural decision. It dictates whether the organization’s AI strategy is tied to a public API, a specific cloud provider, or an internal MLOps capability, with major implications for risk and TCO – plenty of reasons to pause and weigh the upsides here.
- Cloud Providers (Microsoft Azure): High impact. Azure becomes a key value-added reseller for OpenAI’s tech, wrapping it in a lucrative layer of enterprise governance, security, and compliance that creates a powerful, sticky ecosystem and differentiates it from commodity cloud offerings. But here’s the thing: it also ties fortunes together in intriguing ways.
✍️ About the analysis
Researched and written with AI assistance under the editorial responsibility of the i10X News team. The title image is an AI-generated illustration. Read our AI Use Policy. Spotted an error? Request a correction.
This is an independent i10x analysis based on a synthesis of official OpenAI documentation, partner channels like Microsoft Azure and Zapier, benchmark announcements, and open-source tooling guides. It is written for developers, engineering managers, and CTOs tasked with making strategic model selection and AI infrastructure decisions – the folks who, in my experience, need clear-eyed takes to cut through the noise.
🔭 i10x Perspective
What does OpenAI’s model fragmentation really signal for the road ahead? It points to the industrialization of generative AI. The company is evolving from a research-led lab with a singular “magic” model to a mature industrial supplier with a catalog segmented by use case, deployment model, and risk tolerance – a maturation that’s as exciting as it is challenging.
This creates the central tension for the next era of AI: can a single company successfully compete against itself? Will the ease of the general-purpose API cannibalize the high-margin enterprise business on Azure? And will its own open-weight models become “good enough” to hollow out the premium value of both paid channels? These questions linger, don’t they?
The future of AI adoption won’t be decided by which model tops a leaderboard, but by which deployment strategy – API, managed cloud, or self-hosted – wins the long war for enterprise trust and lowest total cost of ownership.